
最新的PRMIA Operational Risk Manager (ORM) - 8010免費考試真題
According to the Basel II framework, subordinated term debt that was originally issued 4 years ago with amaturity of 6 years is considered a part of:
正確答案: C
說明:(僅 Fast2test 成員可見)
The capital adequacy ratio applied to risk weighted assets for the calculation of capital requirements for credit risk per Basel II is:
正確答案: B
說明:(僅 Fast2test 成員可見)
Which of the following credit risk models relies upon theanalysis of credit rating migrations to assess credit risk?
正確答案: C
說明:(僅 Fast2test 成員可見)
Which of the following statements is true:
I. Expected credit losses are charged to the unit's P&L while unexpected losses hit risk capital reserves.
II. Credit portfolio loss distributions are symmetrical
III. For a bank holding $10m in face of a defaulted debt that it acquired for $2m, the bank's legal claim in the bankruptcy court will be $10m.
IV. Thelegal claim in bankruptcy court for an over the counter derivatives contract will be the notional value of the contract.
I. Expected credit losses are charged to the unit's P&L while unexpected losses hit risk capital reserves.
II. Credit portfolio loss distributions are symmetrical
III. For a bank holding $10m in face of a defaulted debt that it acquired for $2m, the bank's legal claim in the bankruptcy court will be $10m.
IV. Thelegal claim in bankruptcy court for an over the counter derivatives contract will be the notional value of the contract.
正確答案: C
說明:(僅 Fast2test 成員可見)
The key difference between 'top down models' and 'bottom up models' foroperational risk assessment is:
正確答案: B
說明:(僅 Fast2test 成員可見)
As the persistence parameter under EWMA is lowered, which of the following would be true:
正確答案: D
說明:(僅 Fast2test 成員可見)
When fitting a distribution in excess of a threshold as part of the body-tail distribution method described by the equation below, how is the parameter 'p' calculated.
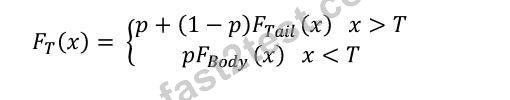
Here, F(x) is the severity distribution. F(Tail) and F(Body) are the parametric distributions selected for the tail and the body, and T is the threshold in excess of which the tail is considered to begin.
Here, F(x) is the severity distribution. F(Tail) and F(Body) are the parametric distributions selected for the tail and the body, and T is the threshold in excess of which the tail is considered to begin.
正確答案: D
說明:(僅 Fast2test 成員可見)
Which of the following statements is true
I. If no loss data is available, good quality scenarios can be used to model operational risk II. Scenario data can be mixed with observed loss data for modeling severity and frequency estimates III. Severity estimates should not be created by fitting models to scenario generated loss data points alone IV. Scenario assessments should only be used as modifiers to ILD or ELD severity models.
I. If no loss data is available, good quality scenarios can be used to model operational risk II. Scenario data can be mixed with observed loss data for modeling severity and frequency estimates III. Severity estimates should not be created by fitting models to scenario generated loss data points alone IV. Scenario assessments should only be used as modifiers to ILD or ELD severity models.
正確答案: D
說明:(僅 Fast2test 成員可見)
Which of the following is not a parameter to be determined by the risk manager that affects the level of economic credit capital:
正確答案: A
說明:(僅 Fast2test 成員可見)